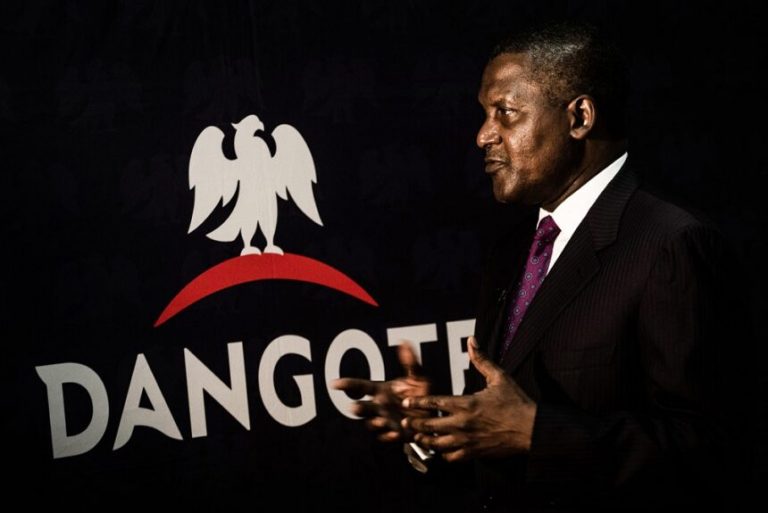
Dangote Group is pursuing a $45bn investment program to expand its industrial businesses and reach $100bn in annual revenue by 2030, with Dangote Cement positioning internally generated cash as a key pillar of its next growth phase.
Dangote Cement, the group’s largest cash-generating business, plans to raise production capacity from 55 million tonnes per annum to more than 80 million tonnes as part of a strategy it describes as “disciplined, self-funded growth whilst delivering on yield.”
The strategy comes with the cement business reporting strong cash conversion and returns on capital. Its cash conversion stood at 89 percent in the 12 months to June 2026, while return on capital employed was 68 percent, according to the company’s September 2026 capital-markets presentation on Monday.
Revenue reached $3.1bn during the 12 months to June 2026, representing a 22 percent year-on-year increase. Adjusted EBITDA recorded a 50 per cent compound annual growth rate between 2023 and 2025, compared with a 40 per cent revenue CAGR over the same period.
The figures provide the financial backdrop to Dangote Cement’s expansion as it seeks to add capacity without abandoning shareholder returns. The company reported a five per cent dividend yield for the 12 months to June 2026, while its dividend grew at a 22 per cent CAGR between 2023 and 2025.
The company’s strategy is also described as capital-light, with existing production assets and logistics infrastructure providing a platform for growth beyond conventional cement. Dangote Cement plans to expand into cement-based adjacencies, including aggregates, mortars, dry mixes, and ready-mix concrete or precast products.
Its African footprint is central to the strategy. Dangote Cement operates across 11 countries, sells into 25 countries, and has 55 MTA of installed capacity. It recorded three million tonnes of export sales in 2025, while 34 clinker shipments were dispatched from Nigeria to Ghana, Cameroon, Côte d’Ivoire, and a third-party customer in Gabon.
Nigeria accounted for 69 percent of FY2025 revenue, while West Africa contributed 13 percent, East Africa 12 percent, and Southern Africa 8 percent. The company said the geographic figures did not total 100 percent because of intercompany transactions.
Dangote Cement’s revenue has risen sharply at the presentation’s consistent exchange rate, from $1.5bn in 2023 to $2.4bn in 2024 and $2.9bn in 2025, before reaching $3.1bn in the 12 months to June 2026.
The company is also using its large resource and logistics base to support expansion. It has about 4.2 billion tonnes of limestone reserves with an estimated 80-year mine life, while its flagship Obajana plant has 16 Mta of installed capacity and about 1.0 billion tonnes of limestone reserves.
At the group level, the $45bn investment plan extends beyond cement into refining and petrochemicals, fertilizer, sugar, and other industrial businesses. Dangote Group is targeting $30bn in adjusted EBITDA by 2030 alongside its $100bn revenue objective.
For investors, the key financial issue is how efficiently Dangote converts its existing operations into cash and capitalizes on those returns as it expands.
The next test will be whether the company can maintain those levels of cash generation and capital efficiency as it moves towards more than 80 Mta of capacity and the wider Dangote Group executes its $45 billion investment program.
“DCP is a differentiated opportunity to invest in Africa’s generational build-out. It is the right platform to capture structural trends that will drive Africa’s build-out and the cement demand shift,” the company said.